Will appear on Buy-Side pages – RECENT BUYER ARTICLES

New SBA Lending Rules: What Business Owners Need to Know Before Selling

The Small Business Administration (SBA) recently updated its lending rules, introducing important changes to how buyers finance business acquisitions. The new Standard Operating Procedure (SOP 50 10 8.1), effective October 1, 2026, imposes stricter underwriting requirements while providing additional flexibility for certain ownership transfers.

Why this matters

SBA-guaranteed loans are a major source of acquisition financing for smaller privately held businesses, particularly transactions involving individual buyers. In fiscal 2025, the SBA approved more than 7,500 business acquisition loans totaling approximately $8.8 billion. Consequently, changes to SBA lending requirements can have a meaningful impact on the pool of qualified buyers and the finance-ability of transactions.

For business owners considering a sale, the bottom line is that some buyers who previously qualified for SBA financing may no longer qualify, while others may be unable to finance the same purchase price.

Key Changes Affecting Business Acquisitions

1. Higher Debt Service Coverage Requirements

For initial acquisitions and owner buyouts, the minimum debt service coverage ratio increases from 1.15x to 1.25x. In other words, the business generally must generate at least $1.25 in qualifying cash flow for every $1.00 of annual debt service.

Lenders must also rely primarily on historical earnings rather than projected improvements. Businesses with declining or inconsistent earnings will be harder to finance, and buyers will have less ability to justify higher prices based on anticipated growth or synergies.

2. Mandatory Quality of Earnings Reports for Larger Transactions

For certain acquisitions with purchase prices of $3 million or more, lenders must obtain an acceptable independent Quality of Earnings (QoE) report.

A QoE examines the reliability and sustainability of reported earnings, including revenue recognition, expense adjustments, working capital, and financial statement reconciliations.

While common in private equity transactions, QoE reports have historically been less prevalent in smaller SBA-financed acquisitions. Sellers should anticipate additional diligence costs and greater scrutiny of their financial reporting and EBITDA adjustments.

3. Stricter Buyer Equity Contribution Requirements

The minimum equity injection for an initial acquisition remains 10% of total project costs. However, seller financing, certain standby debt, and equity from non-controlling minority investors generally cannot collectively satisfy more than 50% of the required injection.

Seller notes counted toward the equity requirement must also remain on full standby for the life of the SBA loan.

These restrictions particularly affect individual buyers with limited personal capital who rely heavily on seller financing. Sellers should verify a buyer’s available equity before accepting an offer.

4. Greater Scrutiny of Business Valuations

SBA lenders must support acquisition financing with an acceptable business valuation. If the purchase price exceeds the supported valuation, the buyer may need to contribute additional equity.

This can create financing challenges when buyers offer aggressive valuation multiples or assign substantial value to anticipated growth. A buyer’s willingness to pay a premium does not necessarily mean that price is financeable.

5. More Flexibility for Certain Ownership Transfers

Not all the changes are restrictive. The new rules distinguish among initial acquisitions, business expansions, owner buyouts, and employee ownership transactions.

Qualifying business expansions and owner buyouts may benefit from reduced equity requirements. Additional flexibility for certain partial ownership transfers and management buyouts may create opportunities for owners considering management succession or a phased exit.

6. Longer Seller Transition Periods

The permitted seller consulting transition period increases from 12 to 24 months for qualifying acquisitions.

This is a welcome change for founder-owned businesses where transferring customer relationships, technical knowledge, and management responsibilities requires time. Longer transitions can reduce buyer risk and support business continuity.

What Should Business Owners and Their Advisors Do Differently?

These changes reinforce several important practices in a well-managed business sale process.

  • Evaluate financing capacity early. A high offer from an undercapitalized buyer may be less attractive than a slightly lower offer from a buyer with committed financing and a greater likelihood of closing.
  • Prepare financial records before going to market. Reliable financial statements, defensible EBITDA adjustments, and organized supporting documentation can help prevent financing delays and purchase price renegotiations.
  • Consider transaction structure. Strategic acquisitions, management buyouts, and phased ownership transfers may offer financing advantages unavailable to first-time individual buyers.
  • Allow sufficient time for financing. Additional underwriting, business valuations, and QoE requirements can extend closing timelines.

The Bottom Line

The SBA’s updated lending rules make acquisition financing more challenging for certain buyers while creating opportunities for others. For owners considering a sale, these changes reinforce an important principle: The highest offer is not necessarily the best offer.

Purchase price matters, but so do financing certainty, transaction structure, and the buyer’s ability to close.

An experienced sell-side M&A advisor can help owners assess buyer qualifications, anticipate financing obstacles, and maintain control and momentum throughout the sale process—improving the likelihood of a successful closing.

—————————–

Exit Strategies Group advises owners of privately held businesses on exit planning, business valuation, and business sales, mergers and acquisitions. For further information or to discuss a potential need, contact Al Statz at 707-781-8580 or alstatz@exitstrategiesgroup.com.

How to Purchase the Company You Work For

For many C-Suite employees, owning the company they work for would be a dream come true. If you’ve been leading a successful private business or are a seasoned member of its executive team, acquiring that business may be a realistic goal.  

Secure Funding

Typically, the biggest hurdle in buying a business is obtaining the cash/equity and securing the debt financing necessary to close the deal. The good news is that a healthy business is an attractive proposition for lenders and equity partners. You’ll need to demonstrate that the business has sufficient cash flow to service the debt and that you (and your team if applicable) have the skills and experience needed to lead the business forward. 

A commercial bank loan is just one potential debt funding source. For smaller businesses, the Small Business Administration (SBA) offers government-backed loans with favorable terms, including long amortization schedules and low equity requirements. In some cases, the current owner may be willing to provide seller financing for a portion of the purchase which, if structured correctly, could act as “equity” in the deal. 

An investment bank may be able to match you with private equity investors looking to support a management buyout.  

Leverage Private Equity

Using your own cash and traditional debt financing may work for a small deal. But to acquired a larger more profitable company you are likely to need a Private Equity (PE) partner. PE firms specialize in investing in businesses with strong cash flows, growth potential and a proven and committed management team. They can enable you to obtain a minority ownership stake and lead the company.

In this scenario, the current owner often leads the sale process with the goal of helping you gain an equity stake. There are literally thousands of PE firms out there, and with you as part of the management succession plan, the pool of potential investors expands.  Finding the right partner is the trick.

PE firms usually arrange the necessary debt financing and structure deals with an ownership stake for essential company leaders – through co-investment or some form of equity appreciation incentives. You may be able to put little to none of your own capital into the transaction and would likely not have to personally guarantee a loan.  

Approach the Owner

If you are interested in owning part of the company you work for, its best to be proactive. The key is to approach the owners early on with a genuine and well-developed interest in acquiring the business. Expressing interest years before the owner plans to sell is okay. There’s nothing unprofessional about asking to own some or all of a business you care about.  

Explain how your experience and leadership will ensure a smooth transition and continued success for the company. You may be best positioned to carry the owner’s legacy forward, maintain company values and culture, ensure customers are well taken care of, and keep the business in the local community.  

If the owner wants to retire soon, you may solve the management succession problem. Even if they’re not planning to phase out, they may see the benefit in offering you a minority stake and keeping you invested in the business long term. Having a strong leadership team with a stake in the company’s future success can be a significant selling point for buyers. 

Seek Professional Advice

Throughout the process, it’s essential to have experienced advisors in your corner. Engage an investment bank or M&A advisor to help with transaction and funding options. Consult an M&A attorney to navigate the legal aspects and an accountant to ensure that the deal is structured in a way that benefits both parties and minimizes potential tax implications. 

Your boss should have their own set of advisors, including an experienced M&A advisor and an attorney to protect their interests and ensure a fair transaction. 

Purchasing the company you work for is an exciting endeavor that requires careful planning, strategic funding, and a strong partnership with your current boss. Talk to your boss and, if they’re amenable, encourage them to consult with an M&A advisor. The right arrangement can enhance business value while providing you with the life-changing opportunity you desire.  


For further information on this subject or to discuss a potential business sale, merger or acquisition need, confidentially, contact Al Statz at 707-781-8580 or alstatz@exitstrategiesgroup.com.
From the M&A Glossary: Caps and Baskets

Indemnity caps and baskets are key terms in business purchase agreements that relate to the seller’s indemnification obligations for any breaches of representations and warranties made by the seller.

Cap

The cap is the maximum amount of damages that the seller will be obligated to pay to the buyer for breaches of reps and warranties. For example, if the purchase price is $40 million and the cap is set at 10%, the seller’s maximum indemnification obligation would be $4 million.

Basket

The basket is the minimum amount of damages that must be incurred by the buyer before the seller is obligated to indemnify the buyer. For instance, if the basket (a true basket, not a tipping basket) is set at $300,000, the seller will only be responsible for indemnifying the buyer for damages that exceed that amount. Baskets help to avoid disputes over small claims and ensure that the seller is not liable for minor or immaterial breaches.

Caps and baskets are heavily negotiated terms in M&A transactions, as they directly impact the allocation of risk between the buyer and the seller. However, rep and warranty insurance can help smooth negotiations.


For further information on this subject or to discuss a potential business sale, merger or acquisition need, confidentially, contact Al Statz at 707-781-8580 or alstatz@exitstrategiesgroup.com.
Exit Strategies Group Advises Custom Ag Formulators in Strategic Sale

Exit Strategies Group is pleased to announce that we recently served as financial advisors to the owners of Custom Ag Formulators (CAF), a North American provider of customized agriculture formulations and products for growers, in the sale of CAF to ICL, a leading global specialty minerals company.  

Founded in 1998 in Fresno, California, CAF offers a diverse assortment of liquid adjuvants and enhanced nutrients, as well as various other specialty products. CAF operates two U.S.-based facilities, with one in Fresno and a second in Adel, Georgia. Both sites manufacture liquid and dry formulations, and their strategic locations mean CAF can ship same day to key growing regions on both the East and West Coasts and to the Central U.S. Visit CAF’s website at customagformulators.com.

“Custom Ag Formulators was founded to provide quality products with custom formulations and packaging in a timely and efficient manner,” said Patrick Murray, principal and director of sales for Custom Ag Formulators. “For more than 25 years, our mission has been to consistently lead the industry in customer service, quality and product innovation, and we are excited to move this mission forward with ICL Group.”

The acquisition of Custom Ag Formulators adds to ICL’s products and expands its presence in the

U.S. ICL employs more than 12,000 people worldwide, and its 2023 revenues were approximately $7.5 billion. The company’s shares are dual listed on the New York Stock Exchange and the Tel Aviv Stock Exchange (NYSE and TASE: ICL). For more information, visit ICL’s website at icl-group.com.

Read ICL’s news release about the acquisition HERE.

This transaction reflects demonstrates Exit Strategies Group’s continued commitment to providing quality merger and acquisition advisory and business valuation services to lower middle market agricultural and manufacturing industries.

—————————–

For more further information or to discuss a potential M&A or business valuation needs, contact Al Statz or Joe Orlando.

M&A Tip: Use Acquisitions to Expand Your Business

In today’s competitive business landscape, standing still means falling behind. Business owners and management must constantly find ways to grow, and one of their most bold and strategic moves is acquiring other businesses. This “buy and build” approach can offer a fast track to expansion, with both benefits and inherent risks. Here we summarize the benefits and risks involved in inorganic growth, and the essential advisors needed to navigate this complex terrain successfully.

Benefits of Growth Through Acquisition

  • Rapid Market Expansion: Acquisitions provide immediate access to new markets and customer bases, bypassing the slow organic growth process. 
  • Diversification: Acquiring businesses in different but related sectors can diversify a company’s revenue streams, reducing dependency on a single market. 
  • Operational Efficiencies: Integrating another business’s operations can lead to cost savings and efficiency gains through economies of scale. 
  • Acquisition of Talent: Bringing in seasoned teams with specialized skills can enhance your business’s capabilities overnight. 
  • Intellectual Property Gains: Acquisitions can bring valuable intellectual property, from patented technologies to brands, which can be leveraged for competitive advantage. 

Risks of Growth Through Acquisition

  • Cultural Misalignment: Integrating two different company cultures poses significant challenges and can impact employee morale and productivity. 
  • Financial Strain: The cost of acquisition, especially if leveraged, can place a significant financial burden on the acquiring company. 
  • Integration Complexities: The logistical challenges of merging systems, processes, and teams can be considerable and disruptive. 
  • Overestimation of Synergies: The anticipated benefits from synergies may not materialize as expected, impacting the acquisition’s profitability. 
  • Regulatory Hurdles: Depending on the industry and scale of acquisition, regulatory approvals can be a complex and time-consuming process.

Navigating Acquisitions with the Right Advisors

To maximize the benefits and mitigate the risks of acquisitions, surrounding yourself with a skilled advisory team is paramount. These experts should include:

  • M&A Advisor/Broker: Specializes in identifying potential acquisition targets, negotiating deals, and guiding business owners through the acquisition process. 
  • Financial Advisor/Accountant: Provides insights into the financial health of potential acquisition targets, evaluates the financial implications of a deal, and ensures the acquiring business can sustain the financial load. 
  • Legal Counsel: Specializes in M&A to navigate contractual details, due diligence, regulatory compliance, and to mitigate legal risks. 
  • HR Consultant: Assists with the integration of staff and alignment of cultures, policies, and benefits between the companies. 
  • Strategy Consultant: Offers an objective viewpoint on how an acquisition fits within the broader strategic goals of your business and can assist with post-acquisition integration planning. 

By leveraging the expertise of these advisors, a business owner can make informed decisions, carefully evaluate potential targets, and execute acquisitions that align with their growth strategy. While acquisitions are not without their challenges, with meticulous planning, thorough due diligence, and strategic execution, they can serve as powerful catalysts for business growth. The key is to balance ambition with careful risk assessment, ensuring that each acquisition not only adds to the company’s assets but also fits seamlessly into its long-term vision and operational framework. 


For further information on this subject or to discuss a potential business sale, merger or acquisition need, confidentially, contact Al Statz at 707-781-8580 or alstatz@exitstrategiesgroup.com.
Is a Quality of Earnings (QoE) Analysis the Same as an Audit?

Not exactly. A Quality of Earnings (commonly called a “QoE”) analysis used in mergers and acquisitions due diligence and a financial Audit serve distinct purposes. Here’s how they differ in terms of purpose, scope of work, timing and reporting:

  1. Purpose:
    • QoE: The primary purpose of a QoE analysis is to assess the sustainability and reliability of a company’s earnings and cash flows. It aims to identify potential risks and irregularities in a company’s earnings that may affect future performance. This analysis is helps acquirers understand the true financial health of a target company and helps them make informed decisions.
    • Audit: A financial Audit, on the other hand, is primarily conducted for compliance and regulatory purposes. It verifies the accuracy of a company’s financial statements and their compliance with generally accepted accounting principles (GAAP) or other applicable accounting standards. While a financial Audit report will make acquirers comfortable with the accuracy of a target company’s financial statements, its focus is not necessarily on assessing the quality or sustainability of earnings and cash flows.
  2. Scope:
    • QoE: A QoE is an “agreed upon procedures” type of analysis and typically involves a review of a company’s financial performance, including revenue recognition practices, expense management, cash flow analysis, reconciliation with bank statements (proof of cash), and potential non-recurring items. Non-recurring items that may distort earnings, include things such as restructuring charges, asset write-offs, or gains/losses from discontinued operations. A QoE may also delve into management’s projections and assumptions about future performance. A QoE may do a deep dive into customer concentration, vendor concentration, employee turnover, age of the workforce, key employees, employee compensation, age of equipment and potential Capex needs, working capital turnover, and profit margin by customer/product/service.
    • Audit: An independent financial audit primarily focuses on verifying the accuracy of historical financial statements and internal accounting procedures. It includes examining transactions, account balances, disclosures, internal controls, and other relevant financial information to ensure compliance with  Generally Accepted Auditing Standards published by the AICPA. A QoE includes some but not all of the procedures conducted in an Audit, and vice versa.
  3. Timing:
    • QoE: QoE analysis is usually conducted during the due diligence phase of an acquisition, after an LOI is signed and before the deal is finalized. This allows the acquirer to gain insights into the target company’s financial performance and identify any potential red flags or areas of concern. The terms financial due diligence and quality of earnings are used interchangeably in the M&A world and are essentially the same thing!
    • Audit: Financial audits are typically conducted annually or periodically, as required by regulatory authorities or stakeholders. They provide a retrospective view of a company’s financial performance for a specific period.
  4. Reporting:
    • QoE: The findings of a QoE analysis are typically presented in a detailed report to the acquirer, highlighting key areas of concern, potential risks, and recommendations for mitigating those risks. The finished product is often an Excel workbook with 30-50 tabs and is sometimes summarized in a PowerPoint presentation deck if requested by the client.
    • Audit: The results of a financial audit are communicated through an auditor’s report, which includes the audited financial statements and a written opinion on the fairness and accuracy of the financial statements. The report may include recommendations for improving internal controls or accounting practices but is primarily focused on providing assurance to stakeholders regarding the reliability of the financial statements.

Buyers almost always obtain an independent QoE analysis as part of their financial due diligence. As sell-side M&A advisors, we help our seller clients decide whether a pre-sale Quality of Earnings analysis would be advantageous.

QoE analyses are conducted by independent CPA firms with dedicated QoE departments. When a sell-side QoE is appropriate, we help our clients select a provider with relevant transaction experience and the capacity to work quickly at a price you can afford.

In summary, while both a quality of earnings analysis and a financial audit involve scrutinizing a company’s financial performance, their objectives, scope, timing, and reporting differ significantly, particularly in the context of acquisitions. A QoE analysis is more forward-looking and strategic, aiming to assess the sustainability of earnings and identify potential risks, whereas a financial audit is retrospective and focused on ensuring compliance and accuracy in financial reporting.


If you have questions about the use of quality of earnings analyses in mergers and acquisitions or want information on Exit Strategies Group’s M&A advisory services, please contact Al Statz at 707-781-8580 or alstatz@exitstrategiesgroup.com. 
M&A Glossary: Quality of Earnings (QofE) Report

A Quality of Earnings (a.k.a. “QoE” and”QofE”) report is prepared by a CPA firm to provide a detailed analysis of a target company’s revenue, expenses, working capital, EBITDA adjustments, etc.

While not an Audit, a QoE provides buyers with important assurances on cash flows and risk. When buyers do this work internally its often just called “financial due diligence”, and when they outsource it, it’s called Quality of Earnings.

See this post comparing a QoE analysis to a financial Audit.

As sell-side M&A advisors, we often recommend a sell-side QofE for companies with more than $10 million in sales and over $2 million EBITDA or when their financials are not clearly organized or their revenue recognition is not straightforward.


For advice on exit planning or selling a business, contact Al Statz, founder and CEO of Exit Strategies Group, Inc., at alstatz@exitstrategiesgroup.com. Exit Strategies Group is a partner in the Cornerstone International Alliance.
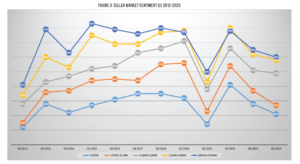
Seller Sentiment Declined in 2023

A seller’s market is when sellers feel they have an advantage or it’s a good time to sell, for instance when demand exceeds supply and there are more interested, active buyers than there are quality deals on the market. In a seller’s market, buyers compete in order to win deals. This typically translates to increased values and more favorable deal terms for the seller.

The results of the latest Market Pulse Survey (Q3 2023) show a decline in confidence year-over-year. This could be due to any number of market headwinds, including high interest rates, inflation, and geopolitical uncertainty.


Small main street businesses face the biggest challenge as they have not seen a seller’s market for a decade now. On the other hand, companies in the $2-50 million range still find themselves in a seller’s market, although the strength of the market has declined in the past year.

Exit Strategies Group operates in this $2-50 million segment of the market, where we are generally able to generate multiple offers and business valuations remain strong.

About the Market Pulse Survey: Each quarter, the M&A Source and IBBA (International Business Brokers Association), in partnership with Pepperdine University’s Private Capital Markets Project, survey North American lower middle market M&A advisors and business brokers and publish the results here.


For advice on exit planning or selling a business, contact Al Statz, founder and CEO of Exit Strategies Group, Inc., at alstatz@exitstrategiesgroup.com. Exit Strategies Group is a partner in the Cornerstone International Alliance.
Representation and Warranty Insurance in M&A

When selling your business, you make a set of promises to the buyer. You “represent and warrant” certain facts about the business. Essentially, you’re certifying that you provided accurate information and there are no known issues pending (e.g., financial, legal, tax, compliance, etc.).


If it turns out those promises are false, the buyer has the right to recoup a percentage of the purchase price. Non-fundamental reps and warranties (typically all items aside from key ownership, legal, and tax items) typically allows the buyer to recoup up to 10-50% (a “cap”) of the transaction if there is a material breach.


At current trends, businesses over $20-$25 million often require an escrow to help fund any breaches in reps & warranties. Smaller transactions, however, will often offset against a seller note or earnout.


On a $20-25 million deal, escrow amounts can commonly be 10-20% of the purchase price, held for a period of 18 – 24 months. On a $30 million deal, for example, the seller might have to delay receiving $3-$6 million of the purchase price until the reps and warranty period has expired.


Representation and warranty insurance offers an alternative to seller escrow. This insurance product is designed to isolate risk and the resulting claims between buyer and seller in the event of a non-fundamental breach in reps and warranties. (Note: Reps and warranty insurance will not cover fraud and intentional misrepresentation.)


Pros and cons of reps and warranty insurance 

For the seller, the advantage of reps and warranty insurance is that they can realize the full value of their purchase price, without holding money in escrow. For many sellers, the holding cost of that money is enough to justify the cost. It also reduces seller risk, for inadvertent, unknown mistakes.


For the buyer, reps and warranty insurance offers a way to collect a claim without jeopardizing their relationship with the seller. Consider a buyer who wants to do multiple deals in the industry. They want the seller to provide a positive referral in the future, encouraging other sellers to work with them.


Similarly, consider a buyer who has retained the seller in a leadership position. They don’t really want to make an expensive claim against their new CEO or sales director. Having reps and warranty insurance protects any ongoing buyer/seller relationship.


Reps and warranty insurance can also expedite the sale process and drive down your legal fees. When sellers know they’re indemnified against certain risks, they don’t have to lobby as hard to protect themselves. To put it simply, negotiations are easier with insurance in place. Conversely, this insurance product requires third party due diligence which can slow the overall process.


What does it cost and who pays?  

Reps and warranty insurance can be purchased by the buyer or seller. Minimum fees are typically $250,000, which makes this product cost prohibitive on smaller transactions. In a competitive market, some buyers will offer to pay or split the cost of reps and warranty insurance with the seller as a way to sweeten their offer.


Sellers need to have adequate representation looking out for their interests. Watch out for exclusions that are overly broad (e.g., an ‘impact of covid’ exclusion) or non-standard for the market.


Be aware that the policy will have a retention figure (like a deductible) – often around 1% of enterprise value. Who covers that retention is another point that needs to be negotiated in your deal terms. Again, we might see a 50/50 split here. So on a $30 million deal, the seller may have to escrow 0.5% or $150,000 (far less than the $3-$6 million escrow estimated above.)


Considerations and alternatives  

Reps and warranty insurance is a newer product on lower middle market deals in the US. Since it’s a relatively young offering, it’s harder for buyers to vet insurance brokers as the track record for payout is not well established. (In other words, the buyer may have a policy, but can they actually collect on it? And what legal fees will they incur in order to collect?)


In cases where buyers are looking for a mechanism to collect without the overhead cost, other options may be more appropriate. For example, if the deal terms include a sellers note, the buyer may prefer to offset a sellers note proportionally to any breach.


Again, sellers should consider that reps and warranty insurance reduces their risk. They may wish to consider that when evaluating buyers and may give some preference to buyers who accept a lower cap (the max amount they can come back for in the event of a breach) or who are willing to cover all or a portion of reps and warranty costs.


For advice on exit planning or selling a business, contact Al Statz, CEO of Exit Strategies Group, Inc., at alstatz@exitstrategiesgroup.com. Exit Strategies Group is a partner in the Cornerstone International Alliance.

Rep and Warranty Insurance Now Available for Deals Under $10 Million

By Patrick Stroth

In recent years, Representations and Warranty (R&W) insurance has become available to smaller and smaller deals.

The eligible deal size dropped to under $20M… then under $15M. This is already quite a feat when you consider that the average transaction value (TV) for deals with R&W coverage in place is $500M. And to be honest, most insurers won’t go lower than $100M—Underwriters are already backed up on processing policies and insurance companies don’t always want to take the time to work on smaller deals that won’t generate large amounts of fees.

Now, for the first time ever, this unique type of coverage is available for deals with a TV of $250,000 to $10M. This opens up R&W coverage to a whole new universe of deals.

How did this breakthrough come about? As with many business ideas, someone saw a gap in the market and decided to fill it with what is officially called Transaction Liability Private Enterprise (TLPE) insurance.

According to CFC Underwriting, the London-based insurer that innovated this new insurance product, there were 230,000 deals in which the TV was between $250,000 and $10M. They decided to create a product for this vast unserved market and came up with TLPE insurance as the first to market solution.

Here are the basics on this coverage, which is available worldwide:

  1.  It covers deals with TV from $250,000 to $10M.
  2.  The policies are sell-side only. (In standard R&W insurance there are sell-side and buy-side policies, although the vast majority are buy-side.)
  3.  It offers competitive terms at rates lower than traditional R&W coverage.
  4.  A streamlined underwriting process to ensure both timely execution and sustainability.
  5.  A deal can be insured up to 100% of Enterprise Value (EV).
  6.  Policy period: six years.

Covered industries include professional services, technology service and product businesses, transportation and aviation, and insurance brokers. CFC generally declines deals involving businesses in healthcare, financial services, oil and gas, mining, pharmaceuticals and regulated industries (such as telecommunications).

How It Works

Similar to standard R&W insurance, TLPE covers innocent misrepresentations made by the Seller to the Buyer.

This provides the Sellers peace of mind because they know they won’t have to risk some or all of their proceeds from the deal in the event of a breach. On the other side, Buyers enjoy a feeling of confidence because there is a guaranteed source of funds available to cover their loss.

Unlike the vast majority of R&W policies, TLPE is strictly a sell-side product. The policy is “triggered” only by a claim brought by the Buyer against the Seller for a loss caused by a breach of the Seller’s representations in the Purchase and Sale Agreement.

As part of this coverage, the Seller is entitled to have their legal defense to contest the Buyer’s claim paid for by the insurer. Underwriters have full authority on the selection of the Seller’s defense counsel, which enables them to control claims costs. The insurance company will also cover any damages or settlement amounts.

Something not in a standard Buyer-side R&W policy is the exclusion for Seller fraud.

While no insurance policy will cover known fraudulent acts, TLPE will pay the legal fees to defend the Seller against allegations of fraud. However, they will cease providing defense costs if actual fraud is established in court.

Important: if the Buyer sues the Seller for something not related to a breach, the insurer does not provide legal defense.

Quick and Easy

TLPE offers streamlined and cost-effective underwriting:

  • An application is required, but Underwriters depend on the Seller’s knowledge of their own business. Who knows the business better than an owner/founder?
  • There are no underwriting fees, which saves policyholders $30,000 to $50,000.
  • No underwriting call is required.
  • The turnaround time is just three days after transaction documentation is submitted and responses to any underwriting questions are provided.

This quick and easy process is possible because the Underwriters are not viewing the reps. They’re not looking at the due diligence collected. They are simply underwriting the application that the Seller provided.

TLPE in Action

TrenData is a Dallas-based SaaS company that offers various human resources services. A larger human resources technology firm was planning to acquire them. The TV was about $5M.

What held up the deal was the Buyer insisted that in the event of a breach of the intellectual property (IP) rep, that the target company would be responsible for any legal expenses or loss. At the same time, the Buyer would retain the sole authority for selecting their own legal counsel and determining the legal strategy.

As the target company noted, this is like essentially writing a blank check. The Buyer could easily hire high-priced attorneys and/or drag the case on and on. They would not go for it.

Neither side would budge on this issue, and it seemed like the deal was lost.

However, less than a week later, the Seller reached out to my firm, Rubicon Insurance Services. We discussed TLPE coverage and how it could work in this deal. The Seller contacted the Buyer, and once they found out that the Seller would pay for the policy, that legal costs would be covered in the event of a loss, and that the deal could be insured up to the full $5M in TV…the gap between the two sides was bridged and the deal closed within a week.

What to Do If You’re Interested in Coverage

TLPE seems simple enough. However, there are key conditions and limitations with this new product. So it’s essential you have an insurance broker experienced in M&A handle the process of securing this coverage.

Something to keep in mind: TLPE policies can be placed post-closing, so if you were unable to get protection for a previous deal, it can actually be revisited.

If you’re interested in seeing if TLPE coverage could be a fit for an upcoming – or past – deal, you can contact Patrick Stroth, at pstroth@rubiconins.com.