Request a Strategy Call and we will get in touch with you
Will appear on Buy-Side pages – RECENT BUYER ARTICLES
Baseball and Business Acqusition Financing: Five Tools Scoring Matrix
The “Hot Stove League” is an expression that describes the six month hiatus from baseball, beginning the day after the final World Series game and extending through the cold winter months until Spring Training opens in March. There is plenty of time and opportunity for baseball fans to roll up their general manager sleeves and discuss the relative merits of potential roster moves on and off their fantasy teams.
- Speed
- Power
- Average
- Fielding
- Arm Strength
- Cash Flow: Can the projected debt service coverage be adequately covered by projected net income.
- Collateral: Does the collateral pledged against the loan represent a significant percentage of liquidation value to loan.
- Management: Does the borrower have significant experience owning and managing a business in the same or related industry.
- Credit: Does the borrower have excellent credit history.
- Down Payment: What percentage loan to value using unborrowed cash is the borrower prepared to inject in the deal.
Small Business Transactions Up 18%, Sellers Earn Higher Sale Prices – According to Industry Report
- The number of closed transactions in Q3 represented both a 17.9 percent increase from last year and the highest number of small business sales recorded in a third quarter since BizBuySell began tracking data in 2007.
- The median sale price for businesses sold in Q3 rose 5 percent compared to last year.
- The average cash flow multiple jumped nearly 9 percent.
- Service-related businesses led the way with a 17 percent increase in closed transactions, while manufacturing was up 16.2 percent and restaurants were up 13.3 percent compared to last year
- In addition to an increased number of closed sales in Q3, there was also a growing number of businesses offered for sale.
- 2014 remains on pace to record the highest number of closed transactions reported since the BizBuySell Insight Report’s inception in 2007.
A Sample Acquisition Due Diligence Checklist
In privately-held business acquisition transactions, as soon as a letter of intent or contingent purchase agreement has been negotiated, the buyer’s in-depth due diligence begins. To kick-start this phase of the transaction, the buyer requests from the seller all of the information that they need to conduct their investigations. Once the buyer is satisfied, the transaction proceeds to the closing phase.
Download Sample Small Business Acquisition Due Diligence Request List
This sample buyer due diligence checklist is a generic list for the acquisition of a small privately-held business. It is for information purposes only. Some of the items listed will not apply to your specific business acquisition and other critical requests will be missing. Please do not use this as an actual request list!
I can’t overstate how important it is to obtain competent legal, financial, tax and other specialized counsel to assist with your due diligence investigations and requests for information. A skilled M&A broker can organize and manage the due diligence process to keep the transaction participants in sync and the deal on track. Often, the broker sets up a virtual data room to which the seller team can upload due diligence documents and from which the buyer team can view and download.
Due diligence is a critical step in every business acquisition. For more information about the due diligence process when selling, merging or acquiring a California business, you can reach Al Statz at 707-781-8580 or alstatz@exitstrategiesgroup.com.
Escrows in California Business Sale Transactions
Business “Transaction Escrows” protect the interests of buyers and sellers, and are used extensively by transaction attorneys and brokers in California. Then there is what’s called a “Holdback Escrow” which secures post-closing obligations and adjustments. This blog introduces you to both types of escrows and how they facilitate business deals.
What is a Business Transaction Escrow?
In California, for business sale-purchase transactions of all sizes and shapes, it is common to have an escrow agent serve as a neutral holder of funds and documents, communications link and closing facilitator. The escrow agent also deals with regulatory compliance, prepares routine transaction documents and closing statements, and handles administrative details in a cost-effective manner.
Business escrow companies in California are either attorneys (acting in a neutral capacity) or they are licensed by the California Department of Corporations. Due to the specialized nature of business escrows, the number of providers is considerably smaller than those serving real estate transactions.
How it Works
Escrow starts with a written agreement between the buyer, seller and escrow holder. The escrow holder prepares written escrow instructions* that reflect the terms of the purchase agreement and all conditions of the transaction. The buyer and seller will sign the escrow instructions, and make any necessary earnest money deposits. The escrow holder will process the escrow in accordance with the instructions. When all conditions are met or achieved, the escrow will be “closed”. The escrow holder provides a concise accounting of all funds, and arranges for the safe delivery of all funds and documents to their proper recipients.
* When applicable, these instructions will include a Notice to Creditors of Bulk Sale. California’s Bulk Sale law is contained in Commercial Code Section 6101-6111.
The typical duties of an escrow holder in a business asset sale/purchase transaction include:
- Requesting publication, recording and UCC lien searches for state and county
- Complying with Bulk Sale statutes (publication), as applicable
- Notifying the county tax collector
- Requesting a beneficiary’s statement if debt or financial obligations are to be taken over by the Buyer
- Requesting demands from existing lien-holders, receiving claims
- Notifying and obtaining clearances from County, State and Federal agencies as required
- Complying with lender’s requirements, securing loan documents and receiving funds
- Obtaining and holding purchase funds from the buyer
- Prorating taxes, interest, rents, security deposits, etc., as instructed
- Preparing routine legal and financial documents such as notes, security agreements, personal guarantees, amortization schedules, deeds of trust, UCC-1 financing statements, bill of sale, corporate resolution authorizing the transaction, etc.
- Can prepare fictitious business name statements
- May prepare routine amendments to agreements
- Securing releases of all contingencies or other conditions imposed on the particular escrow
- Preparing estimated closing statements prior to close of escrow
- Consultation regarding problems that arise
- Preparing final closing statements for the parties, accounting for the disposition of all funds deposited in escrow
- Obtaining appropriate signatures on all documents
- Close escrow when all instructions of buyer and seller have been carried out
- Disbursing funds as authorized by instructions, including commissions and payoff liens
- Preparing and recording UCC-1, UCC-3 and deeds of trust, as needed
- Securing tax clearances
- Distributing final transaction documents to all parties
The above list is a generic set of escrow tasks in a sale of business assets. The escrow tasks performed in an actual transaction will depend on the transaction type and circumstances, and will be listed in the instructions prepared by the escrow holder. Stock sale escrows look a lot different, and are typically simpler.
The Holdback Escrow and How it Works
No. In some Merger and Acquisitions (“M&A”) transactions, the buyer and seller agree to place a portion of the purchase price in a third party escrow account for a specified period of time after closing. These funds are intended to secure payment to indemnify the buyer against losses caused by a breach of the seller’s representations, warranties or covenants; for payment of post-closing working capital or balance sheet adjustments; to guaranty payment of an earn out (where part of the purchase price is based on post-closing performance of the business), as collateral to insure the performance of some other event by the seller; or some combination of these. Holdback escrows go by other names, such as “retention escrow”, “indemnity escrow” and “holding escrow”.
Both buyers and sellers can benefit from holding back funds in escrow. Holdback provisions should be carefully thought out and negotiated early in the M&A negotiation process. Understanding the typical approaches and common pitfalls is extremely helpful, which only comes with experience.
Holdback escrows are often completely separate from the transaction escrow. The escrow holder may be a bank, trust company, or other professional service provider. Typically, funds from the transaction escrow roll over into the holdback escrow immediately after a transaction closing. A holdback escrow requires a separate agreement between the escrow agent, buyer and seller, which includes, among other things, conditions for releasing funds and procedures for resolving any disputes. This can take some time to negotiate.
If you have questions regarding this blog post or need help selling or acquiring a California company, you can Email Al Statz or call him at 707-778-2040. And if we don’t know the answer we would be happy to direct you to someone who does!
What is an Earn-out?
An earn-out is when part of the consideration received for a business is based on future sales or earnings. Earn-outs usually come in to play in business acquisitions when a business has high risk factors, or when non-linear growth is reasonably expected, or when there is a significant gap in the price expectations between the buyer and seller. In all cases the parties share the risk and reward of future performance.
Bridging a Price Gap
An earnout is often the best way to bridge a gap between what a seller will accept and what a buyer will pay. For example, a seller may think their company is worth $4 million and the buyer thinks it’s worth $3 million. They can agree on a guaranteed price of $3 million, plus an earn-out over a period of 1-2 years, structured to provide the seller with the potential of receiving the extra $1 million, or more if sales or earnings reach a certain level, based on an agreed upon formula.
Devil in the Details
While simple in concept, earn-outs can become contentious during the measurement and payout phase. It is critical that earn-out parameters be carefully thought out and clearly defined in the purchase agreement. There must be no ambiguity in the accounting practices to be used, for example. Even if you continue to manage the business during the earn-out period, don’t assume anything.
At the same time, remember the K.I.S.S. principle. In my experience, the more complicated an earnout gets, the more likely negotiations will fail. It is usually (though certainly not always) best to base earn-out calculations on top-line sales or gross profit, not net income. Also, be sure to design the earnout formula to completely align the interests of the parties.
For another perspective on the use of earnouts in M&A transactions, see this recent article on Axial Forum.
For more information on M&A transaction structuring strategies, or if you want help selling a business or developing a winning exit strategy, contact me at 707-778-2040 or alstatz@exitstrategiesgroup.com.
Why do business owners hire an M&A broker?
Recent clients “Jane and John Doe” were satisfied with the market value estimate of their manufacturing business, as determined by the independent valuation we prepared. Armed with this essential piece of information, they were ready to sell the business they had founded and grown with much effort over many years.
John thought they should try to sell the business themselves. After all, weren’t they the best salespeople for their business? And why should they share a portion of the proceeds with a broker? Jane was not so sure and began to research whether hiring a business transaction intermediary was warranted.
One article that Jane found contained the results of a poll conducted by Partner On-Call Network LLC in which sellers of small and medium sized businesses were asked why they hire business brokers instead of trying to sell themselves. The poll identified 62 reasons, including these top eight, in order of frequency cited:
- Brokers know how to sell businesses; most sellers don’t
- Seller doesn’t want to be distracted from running business
- Confidentiality preservation and knowledge of what/when to show buyers
- Access broker’s database of potential buyers and investors
- Maximize price buyers will pay for the business
- Owner does not know how to find buyers
- Prepare owner to sell and prepare business for sale
- Broker understands and can depersonalize negotiations
After discussing this and other inputs that they had received, the Doe’s decided that hiring an intermediary was the prudent decision if they wanted to maximize proceeds from the sale of their business and reduce the risk of no deal or a flawed deal.
All 62 reasons can be found HERE.
For a certified business valuation or assistance with successfully exiting your California company, you can Email Jim Leonhard or call him at 916-800-2716.
What Sells Businesses? Quality Information.
- Company History
- Ownership, Owner’s objectives
- Products and Services
- Customer Base
- Suppliers
- Industry
- Competition
- Employees & Independent Contractors
- Management & Key Individuals
- Operations
- Tangible Assets
- Intangible Assets
- Facilities and Lease Terms
- Systems & Technology
- Sales & Marketing
- Relationships
- Strengths, Weaknesses, Opportunities and Threats
- Financial history, normalized*
- Financial forecast, when appropriate
Reducing Cost of Capital in a Small Business Acquisition
Small Business Administration (SBA) guaranteed loans are widely recognized as one of the only reliable sources of third-party funding for small privately-held business acquisitions (up to $5 million), but do you know how this benefits the borrower’s cost of capital?
Very few small business transactions are completed in which the buyer pays all cash. This is not just because most people don’t have a big pile of cash lying around; it’s also because financial leverage lowers the overall cost of capital in any investment where an income stream is expected. And every business broker knows that it also allows a buyer to purchase a larger, more profitable business.
SBA debt financing for business acquisitions currently “costs” around 6% (interest). The cost of equity financing is much higher — typically 20 to 25% or more — depending upon the risk level of the investment. The risk is much higher for the portion not financed by SBA because if cash flow from operations declines for any reason, it’s the buyer’s cash flow (and return on equity investment) that suffers. The greater the risk, the greater a rational buyer’s expected rate of return will be. In other words, an equity holder’s cash flows are riskier than a bank’s, so they require a higher rate of return. Also, in the event of a liquidation, the debt holder has preference.
How is cost of capital calculated?
If a buyer is able to obtain 6% money from the SBA on 70% of the purchase price of a $1,000,000 business acquisition, and the buyer expects a rate of return of 25% on the remaining 30% (equity portion of capital structure), the weighted average cost of capital is:
Debt 70% x 6% = 4.2%
Equity 30% x 25% = 7.5%
Weighted Average Cost of Capital = 11.7%
This means that by leveraging the business acquisition, the buyer will see greater rates of return from the profits generated; not a bad reason to “leverage the deal.”
By the way, what amount of Fair Market Value will an SBA lender lend?
Subject to the buyer’s qualifications (of course), SBA lenders typically loan 70% (more in certain cases) of an agreed upon asset sale/purchase price plus an amount for working capital (lenders call it “over-funding” the loan). SBA regulations for 7(a) loans require that the sponsoring bank obtain an independent business appraisal from a qualified appraiser for any loan with an intangible (goodwill) value component over $250,000; or for any amount when the business is being sold to a family member. This is a great check and balance for the buyer to be sure the business isn’t over-valued.
When the appraised fair market value of the business comes in below the agreed upon purchase price, the SBA lender can still lend, but only up to 70% of the appraised Fair Market Value. Here the buyer is usually faced with two choices: (1) pay the incremental amount over the appraised value and increase their cost of capital; or (2) re-negotiate with the seller to lower the price.
“The Importance of a Proper Valuation” is the subject of my next Blog … so stay tuned.
Bob Altieri, CBA (Certified Business Appraiser) appraises businesses for SBA lenders throughout California. For additional information or for advice on a current need, please do not hesitate to call Bob.
Do Strategic Buyers Share Synergies with Sellers?
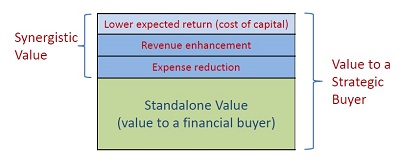
In successful M&A deals involving substantial synergies, the deal price usually falls in the range between the standalone fair market value of the target business and that value plus the full value of potential synergies.
Value of potential synergies?
Increased value (over and above fair market value) to a strategic buyer, involves synergies between the acquired and acquiring firm and the additional financial returns and therefore value created by those synergies . There is a “1+1=3” effect in the acquisition process. Synergies come in various forms, including an ability to increase revenues of the target firm, cost savings by eliminating redundancies or achieving economies of scale through combining of business units; and the reduction of risk through, for example, increased size and stability, greater management depth or vertical integration.
How much of this synergistic value component is paid in practice?
Buyers pay, on average, 31% of the average capitalized value of expected synergies to sellers, according to recent research by the Boston Consulting Group. The March 2013 BCG article, titled “How Successful M&A Deals Split the Synergies”, can be viewed here.
From an acquirer perspective, why pay for synergies at all?
Because sellers usually anticipate buyers’ synergies and demand to be paid something for them, particularly when multiple strategic buyers are present. In addition, when the buyer is a public company , markets usually react favorably and boost the value of the acquirer when a strategic acquisition is announced. Of course, this increase in value may vanish if the synergies don’t actually materialize! When paying more than fair market value, strategic acquirers must be certain that there will be synergies in the combination. They do not randomly shell out big bucks. The owners of firms that appeal to strategic buyers have a greater opportunity to maximize value in an M&A sale process.
However, not every firm is a strong candidate for a strategic sale.
Most willing buyers for small companies are financial buyers who will operate the business similarly to the way it is operating now, and are normally willing to acquire a company for fair market value. Individual owner-operators, management employees and private equity buyers are examples of financial buyers.
We are always happy to discuss how buyers would typically value of your company. Valuations play a part in all strategic transactions, tax, and many litigation matters. For additional information or advice on a current situation, please do not hesitate to call.
– See more at: https://www.exitstrategiesgroup.com/blog.html?bpid=3676#sthash.rrhDOJwx.dpuf